Florida Roof Insurance Claims, From the Roofer to the Lawyer
A storm-damaged roof passes through many hands before it is fixed and paid for. The deadlines that matter in Florida, and who does what from the first ladder to the last resort.
A Florida roof claim runs on a clock, and the clock starts with the storm. For a hurricane, the law sets the date of loss as "the date that the hurricane made landfall," and four deadlines count from there:
- Report a new or reopened claim within 1 year of the date of loss, and a supplemental claim within 18 months (section 627.70132).
- Expect the insurer to begin its investigation within 7 days of receiving your proof-of-loss statements, and to make any physical inspection within 30 days (section 627.70131).
- Expect a copy of any detailed estimate from the insurer's adjuster within 7 days after it is written.
- Expect the insurer to pay or deny the claim, or a portion of it, within 60 days of your notice, with a written explanation.
Most of those numbers date to December 2022, when Senate Bill 2-A cut the window to report a claim from 2 years to 1 and the time to pay or deny from 90 days to 60.
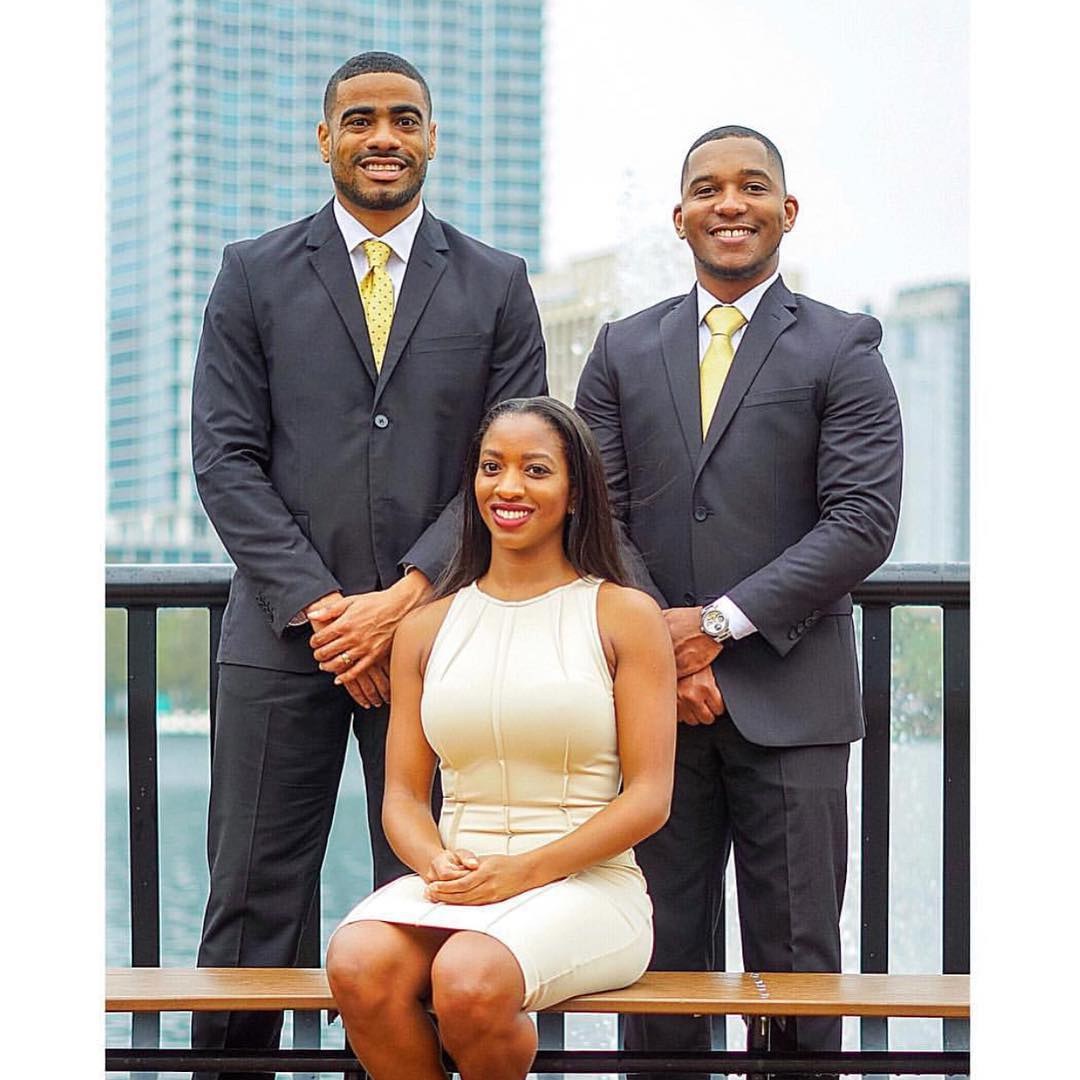
Attorney Erica G. Burns works with that clock. A partner at Purely Legal in Orlando, she handles first-party property insurance claims, the homeowners insurance kind, alongside a practice centered on family law. Between the first ladder and the last check, a roof claim passes through a whole crew, and the lawyer is the last of them. Here is who does what.
The Roofer and the 25 Percent Rule
The roofer is the one on the ladder, and what they can replace depends on when the roof went on. Florida's building code long held that no more than 25 percent of a roof could be repaired or replaced in a 12-month period unless the whole roof met the current code. A 2022 law, Senate Bill 4-D, changed that for roofs built, repaired or replaced under the 2007 Florida Building Code or later: on those roofs, only the portion being worked on has to meet the current code.
One thing a roofer can no longer take is the claim itself. For residential policies issued on or after January 1, 2023, SB 2-A prohibits assigning post-loss insurance benefits, in whole or in part, so the claim stays with the homeowner.
The Insurer's Adjuster
The adjuster works for the insurance company and sizes up the loss for it. Florida law asks three things of that visit:
- The adjuster who inspects must give you a printed or electronic document with their name and state license number, and every later message about the claim carries the same (section 627.70131).
- The insurer may investigate electronically, with photos, video calls or drone footage, and may let you use those methods too.
- Anyone acting for the insurer must give at least 48 hours' notice before an onsite inspection, and you may refuse access if that notice was not given (section 626.854).
The Public Adjuster
A public adjuster is licensed to work the claim for the homeowner instead. Their fee comes out of the payment, and Florida caps it: 10 percent for claims from an event the governor declared an emergency, during the year after that declaration, and 20 percent otherwise (section 626.854). A public adjuster may solicit only Monday through Saturday, between 8 a.m. and 8 p.m. You can cancel their contract without penalty within 10 days of signing; after a declared emergency, you get 30 days from the date of loss or 10 days from signing, whichever is longer.
Signs a Claim Is Stalling
Florida's deadlines turn a slow claim into something you can measure. Purely Legal's guide to an insurance company that is stalling lists the warning signs:
- Frequent requests for more information.
- Slow answers and poor communication from the adjuster.
- A denial for questionable reasons.
- Weeks or months of delay on basic steps, like the inspection.
- An offer well below what the claim is worth.
Against those signs, the firm's guide gives the homeowner a paper trail. Log every call and message in writing, with dates, times and the names of the people you spoke to. Put every request for action or a status update in a formal letter sent by certified mail, with a reasonable deadline to answer. If the delay goes on, a complaint to the state's insurance regulator and a lawyer are the next steps. In Florida, the 7-day, 30-day and 60-day marks above are the measure a log is held against.
The Mediator
When the payment and the estimate do not match, Florida offers a step before appraisal or court. The state's mediation program for residential property claims (section 627.7015) opens once the insurer has paid or denied the claim, or chosen to reinspect. The insurer bears the cost of the conference, the homeowner may bring a lawyer, and the result is not binding. If the two sides sign a settlement, the homeowner has 3 business days to take it back, unless they have already cashed the check.
The Lawyer and the Notice Before a Lawsuit
The last hands on a stalled claim are a lawyer's, the part of the crew Burns belongs to. Before any suit, Florida requires a written notice of intent to initiate litigation, filed with the Department of Financial Services "at least 10 business days before filing suit" and not before the insurer has decided coverage. The insurer must answer in writing within 10 business days, and a court must dismiss a suit filed without the notice. Since SB 2-A, the old rule that made an insurer pay a winning homeowner's attorney fees no longer applies to property insurance suits; either side can recover fees through the offer of judgment statute instead.
The notice rule made news this fall. On October 22, the Florida Supreme Court ruled unanimously that the requirement, which took effect July 1, 2021, did not apply to a homeowner's 2021 lawsuit over a 2019 water damage claim, WLRN reported. The decision settled years of conflicting appeals court rulings over whether the law reached back to older policies.
After the Check Clears
A settled claim ends where it started: the roofer back up the ladder, replacing the section the adjuster measured, under a code that now asks only that the new part be new.
Highlights
How long do you have to file a roof insurance claim in Florida
A new or reopened claim must be reported within 1 year of the date of loss, and a supplemental claim within 18 months, under section 627.70132. For a hurricane, the date of loss is the day it made landfall.
How long does a Florida insurer have to pay a property claim
The insurer must pay or deny the claim, or a portion of it, within 60 days of receiving notice, and explain its decision in writing, under section 627.70131.
Do you have to notify the state before suing your homeowners insurer in Florida
Yes. A written notice of intent to initiate litigation goes to the Department of Financial Services at least 10 business days before filing suit, under section 627.70152. In October 2026 the Florida Supreme Court ruled that the requirement did not apply to a lawsuit over a claim from before the law took effect.
Sources
- The Florida Senate: section 627.70132, notice of property insurance claim
- The Florida Senate: section 627.70131, insurer's duty to acknowledge and act
- The Florida Senate: SB 2-A (2022) bill summary
- The Florida Senate: SB 4-D (2022) bill summary
- The Florida Senate: section 626.854, public adjusters
- The Florida Senate: section 627.7015, mediation of property insurance claims
- The Florida Senate: section 627.70152, suits arising under a property insurance policy
- WLRN: Florida Supreme Court opens door to some lawsuits against insurers
- Purely Legal: Erica G. Burns
- Purely Legal: What to Do if the Insurance Company Is Stalling






